

The global smartphone market suffered its worst third quarter in 14 years in 2026, as rising memory chip costs and supply shortages forced manufacturers to reduce shipments and increase prices. According to preliminary estimates from Counterpoint Research, worldwide smartphone shipments fell 20% year-on-year in the July-September quarter, reaching their lowest third-quarter level since 2012.
The downturn highlights how surging demand for artificial intelligence infrastructure is affecting consumer electronics, creating a shortage of memory components used in smartphones and other devices.
AI Boom Creates Memory Chip Shortage
The growing demand for AI data centres has intensified competition for DRAM and NAND memory chips. These components are essential for smartphone operations and data storage, but suppliers are prioritising demand from AI infrastructure customers.
As memory prices climb, smartphone manufacturers face higher production costs. Companies have responded by raising retail prices, reducing shipments and adjusting their product portfolios to protect profit margins.
The shortage has also made it difficult for manufacturers to maintain affordable prices in the entry-level and mid-range smartphone segments, where buyers are particularly sensitive to price increases.
Samsung Retains Global Market Leadership
Samsung remained the world’s largest smartphone manufacturer during the third quarter, accounting for 23% of global shipments. Its shipments declined by just 3% compared with the same period last year, making it relatively resilient amid the wider market contraction.
Demand for its Galaxy Z Fold8 series supported performance in the premium segment, while stable component supplies helped the company maintain availability of mid-range devices.
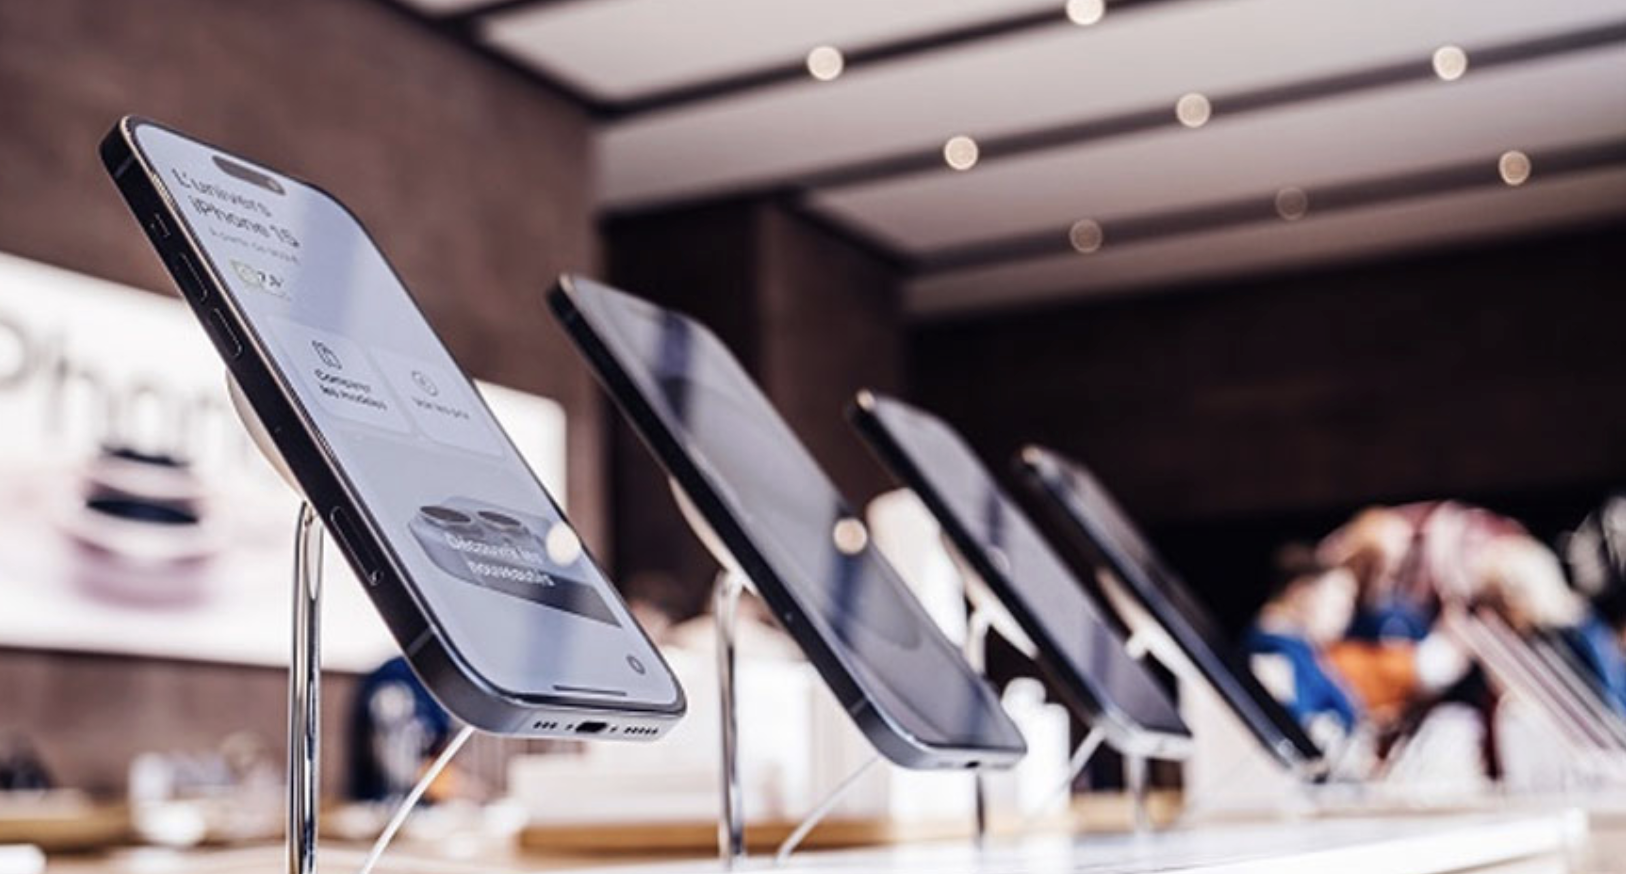
Apple secured a 22% market share, crossing the 20% mark for the first time in a third quarter. However, its shipments also declined year-on-year. The absence of a standard iPhone 18 model during the launch period contributed to a smaller initial shipment volume compared with the previous year’s iPhone launch cycle.
Xiaomi, Oppo and Vivo Face Steeper Declines
Chinese smartphone manufacturers experienced sharper declines as rising component costs put pressure on their more price-sensitive product portfolios.
Xiaomi recorded a shipment decline of more than 30%, reducing its global market share to 10%. The company scaled back its exposure to lower-priced devices and selected overseas markets to avoid selling products at unprofitable margins.
Oppo and Vivo also recorded shipment declines exceeding 20%. Both companies increased prices across entry-level and mid-range models in response to higher memory costs.
The trend suggests that manufacturers with strong purchasing power, reliable component supplies and established premium portfolios may be better positioned to withstand the downturn.
Smartphone Buyers May Face Higher Prices
The shortage is changing consumer behaviour, with buyers holding on to their existing devices for longer and increasingly considering refurbished smartphones.
Higher component costs are also widening the gap between premium and budget devices. While demand for premium models has proved relatively resilient, price-sensitive consumers face fewer affordable choices.
Manufacturers are expected to continue prioritising profitability over shipment volumes, streamlining product portfolios and focusing on higher-value devices.
Summary
Global smartphone shipments fell 20% year-on-year in the third quarter of 2026, reaching their lowest level for the period since 2012. Rising DRAM and NAND prices, driven partly by AI data centre demand, have increased manufacturing costs and retail prices. Samsung led the market with a 23% share, followed by Apple at 22%, while Xiaomi, Oppo and Vivo recorded sharper declines.